Your employer drops the phrase “401(k) plan” during onboarding. Your brain? Gone. Total blank. That’s not a personal failure; millions of workers hit the same wall every single day, unsure what a 401(k) even is, let alone why it should matter to them. Here’s the thing, though: you don’t need a finance degree to figure this out. The basics are genuinely manageable. This guide cuts through the noise so you can make real decisions about your retirement savings, without the headache.
What a 401(k) Plan Actually Is
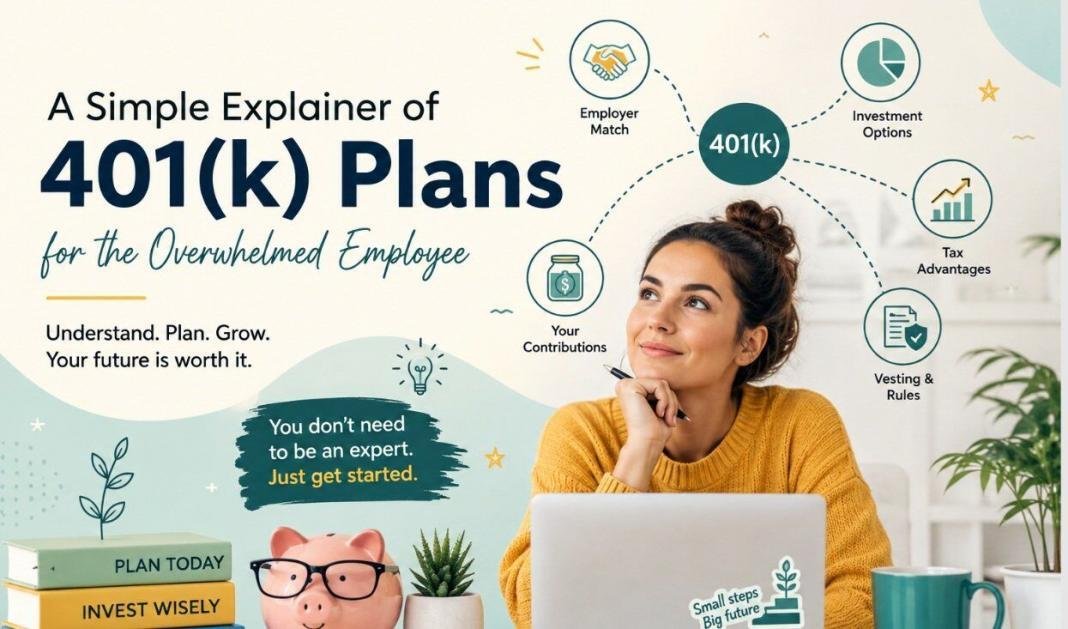
Think of a 401(k) as a retirement savings account tied to your job. You set aside a slice of your paycheck before taxes bite into it. Your employer sponsors the whole thing; you decide how much to contribute each pay period, within limits the IRS sets. That money doesn’t just sit there gathering dust; it gets invested in options you pick, like mutual funds or target-date funds, and grows over time. When you retire or leave the company, you can pull that money out. Rules apply, of course, depending on your age and the type of plan you’re in. The name itself? Straight from section 401(k) of the Internal Revenue Code, written into law back in 1978. Dry origin story, genuinely useful tool.
How Your Contributions and Employer Match Work
Here’s where it gets interesting. Many employers will match a portion of what you put in — essentially dropping free money into your account. Say your employer matches 50 percent of contributions up to 6 percent of your salary. You earn $50,000 a year, contribute 6 percent ($3,000), and your employer adds another $1,500. Just like that. Not every company offers this, but when yours does? Walking away from that match is leaving guaranteed money on the table. Capturing the full employer match can be one of the most valuable early-career retirement-saving opportunities available to you.
Pre-Tax Versus After-Tax Contributions
Traditional401(k) contributions come out of your paycheck before income taxes are calculated. That shrinks your taxable income for the year — so your federal tax bill drops. Contribute $500 a month, and that’s $500 less income the IRS can tax. Some employers also offer a Roth 401(k). Different setup: you contribute after-tax dollars now, but qualified withdrawals in retirement can generally be tax-free. Which one’s better? Depends on your current tax bracket and what you expect your tax situation to look like decades from now. Neither is universally right. The key is knowing the difference exists so you can actually choose.
Investment Options and How They Grow
Your contributions aren’t parked in some low-yield savings account. They go into investment options your employer’s plan offers — stocks, bonds, target-date funds. Target-date funds, specifically, are a lifesaver for the overwhelmed. You pick the fund closest to your expected retirement year, and it automatically shifts its investment mix as you age. Less decision-making. Still growing. Over decades, compound growth does heavy lifting you can barely imagine when you’re 25. Starting early, even with small amounts, gives that compounding process the time it needs to really build something.
Vesting, Withdrawals, and Penalties
Vesting is about ownership. Your own contributions? Always yours. The employer match is a different story. Some companies hand it over immediately; others use a vesting schedule that requires you to stay for a set period before that match fully belongs to you. Know your schedule. It matters more than most people realize, especially if you’re considering a job change. Pull money out before age 59½, and you’re typically looking at a 10 percent early withdrawal penalty on top of regular income taxes. Ouch. Exceptions exist: medical emergencies, certain hardships, but treat those as last resorts, not Plan B. Your 401(k) is a retirement account. Not an emergency fund.
Getting Started With Your Plan
The setup is usually less painful than people expect. During onboarding or open enrollment, your employer hands you plan documents and access to a provider’s website. You pick a contribution amount, choose your investments, and name your beneficiaries. Feeling lost by the investment lineup? Target-date funds can be a useful option for overwhelmed investors. Simple. If you’re unsure how your 401(k) contributions fit into your broader financial situation, consider speaking with a qualified financial or tax professional. And you can always adjust contributions later during open enrollment or when life shifts.
Conclusion
A 401(k) is one of the most accessible retirement-building tools many employees have access to. Traditional 401(k) contributions can reduce your taxable income today, while both Traditional and Roth 401(k)s can help you build retirement savings for the future. The investment details and tax rules can feel intimidating at first. But consistent contributions can matter more than finding a perfect strategy. Start with what you understand, take advantage of any available employer match, and adjust your contributions as your circumstances change. Your future self won’t care that you felt overwhelmed at the beginning; only that you started.
You may also like to read,
- How to Start Saving Your Side Hustle Income for Retirement
- 5 Methods to Boost Collaboration In a Virtual Workplace